Seller-Paid Rate Buydowns: The Fix for High Rates
Rates are high. You don't have to wait them out.
A seller-paid rate buydown can lower your payment starting on day one, and it costs you nothing as the buyer.
Most buyers have never heard of it.
That's exactly why Scott Christian and I started our new podcast.
I'm Patti Gregory with Haven Realty Group.
Scott is a lender with Christian Brothers Lending, powered by Arbor Financial Group, with 40 years in the business.
We met at an open house years ago, where Scott showed up with a full barbecue setup and turned the driveway into a party.
Now we're bringing that same easygoing energy to real conversations about buying a home.
In episode 1, we tackled the question every buyer is asking: what do I do about these rates?
What a temporary buydown actually is
A temporary buydown lowers your interest rate for the first one, two, or three years of your loan.
The seller pays for it as a concession when you negotiate the deal.
Think of it as a staircase:
- Year 1: your lowest rate and lowest payment
- Year 2: a step up, but still below the full rate
- Year 3 and beyond: your full note rate
The most common version is the 2-1 buydown.
Your rate starts 2% below the full rate in year one, then 1% below in year two.
A 3-year buydown saves even more, but it costs the seller more to fund.
And here's the part buyers love: if rates drop and you refinance, you can step off the staircase whenever it makes sense.
The same $20,000, two very different results
On a $1,000,000 purchase with 20% down, a seller concession saves you about seven times more than a price reduction.
Scott ran the numbers the morning we recorded.
|
Your offer |
What the seller gives up |
What you save over 2 years |
|---|---|---|
|
$20,000 off the price ($980,000) |
$20,000 |
About $2,600 |
|
$20,000 seller concession for a 2-1 buydown |
$20,000 |
Almost $19,000 |
Same cost to the seller.
A completely different outcome for you.
Not buying at a million?
No problem.
The concession scales with your price point, and Scott's calculator shows your exact savings in minutes.
Why waiting for rates to drop can cost you more
When rates fall, buyers flood back in, and prices go up.
That means competing offers.
Higher price points.
And sellers who have no reason to give you a concession.
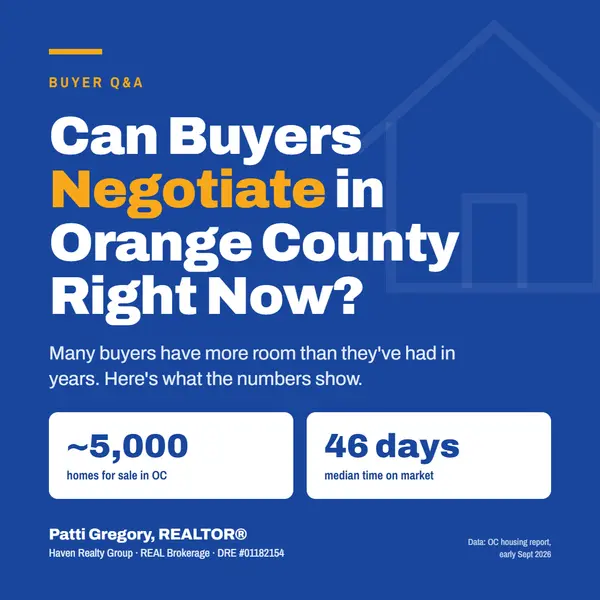
Right now, the leverage is on your side:
- More inventory than buyers. You have real choices.
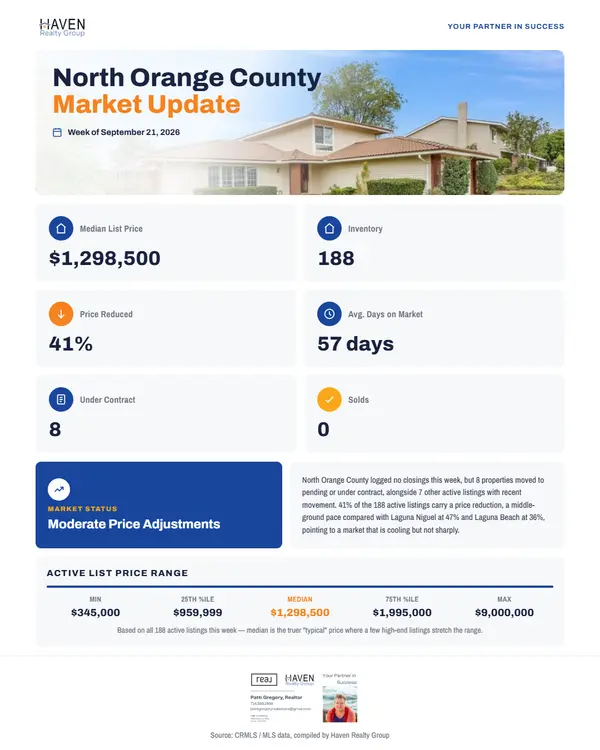
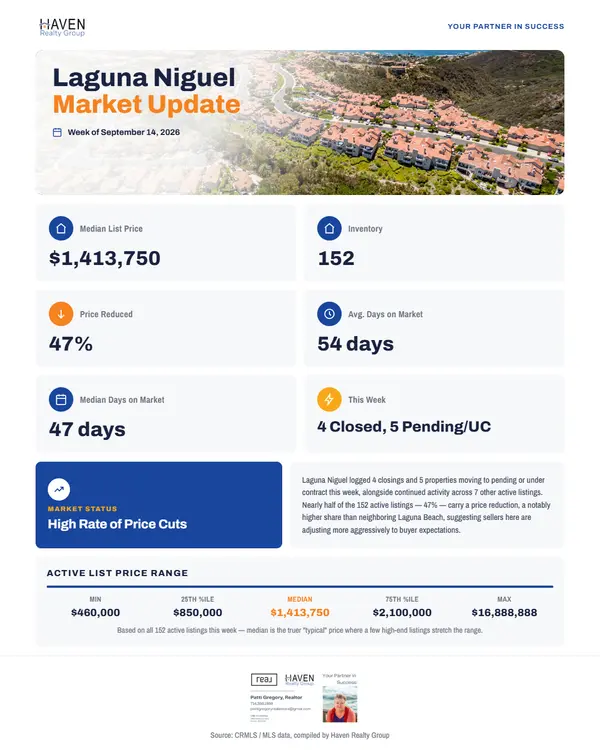
- Sellers are already cutting prices. In Laguna Niguel, 43% of listings had price reductions in a single week.
- Fall is a slower season. Fewer buyers are out shopping for homes.
That's why we're calling this the perfect market for buyers.
Nobody else is saying it.
Buy now with a buydown, and when rates drop and buyers rush back in, you already own the home and you're already ahead.
Negotiate terms, not price
The smartest offer in this market isn't always the lowest one.
It's the one with the best terms.
A price cut shaves a little off your payment for 30 years.
A seller concession for a buydown lowers your payment from the very first month.
If rates drop, you don't lose a dime
If you refinance before the buydown runs out, the unused funds still work for you.
Here's how it plays out:
- The seller funds $20,000 for your 2-1 buydown.
- After year one, you've used about $12,500 of it.
- Rates drop, and you refinance.
- The remaining $6,384 goes toward your principal balance or your refinance costs.
It doesn't come back to you as cash.
You can't take it to Vegas.
But it's still your money, working for you.
So you get the benefit from day one, not just if you stay the full two years.
The one thing to know before you start
You still qualify at the full note rate.
Your lender makes sure you can afford the payment after the buydown ends.
That's a safeguard, not a setback.
It means your budget works in year one, year two, and every year after.
See your numbers before you make an offer
You don't have to guess what a buydown could save you.
Send us your price range, and Scott will run your exact savings for one, two, or three years.
Zero pressure.
Just real numbers, so you can make a confident decision.
Watch the full episode: The FIX to higher rates
Reach out to Patti: 714.398.1998 pattigregoryrealestate@gmail.com
Reach out to Scott: 949.456.2455 scott@cbrosinc.com
Coming up on the podcast
New episodes drop every week.
Here's what's next:
- First-time buyers: where to start
- Contingencies, explained
- What escrow and title actually do
- Closing costs, with no surprises
- Lender lingo, translated
- Non-QM loans: options beyond Fannie, Freddie, and FHA
Got a question you want us to answer?
Drop it in the YouTube comments or send it to either of us.
We'll put it on the list.
Patti Gregory, REALTOR® | Haven Realty Group | REAL Brokerage | DRE #01182154
Scott Christian | Christian Brothers Lending, powered by Arbor Financial Group | NMLS # 316101 | DRE 00922253
Figures are an example based on a $1,000,000 purchase with 20% down at rates available when recorded. Rates, programs, and savings vary. Not a commitment to lend.
Categories
Recent Posts